
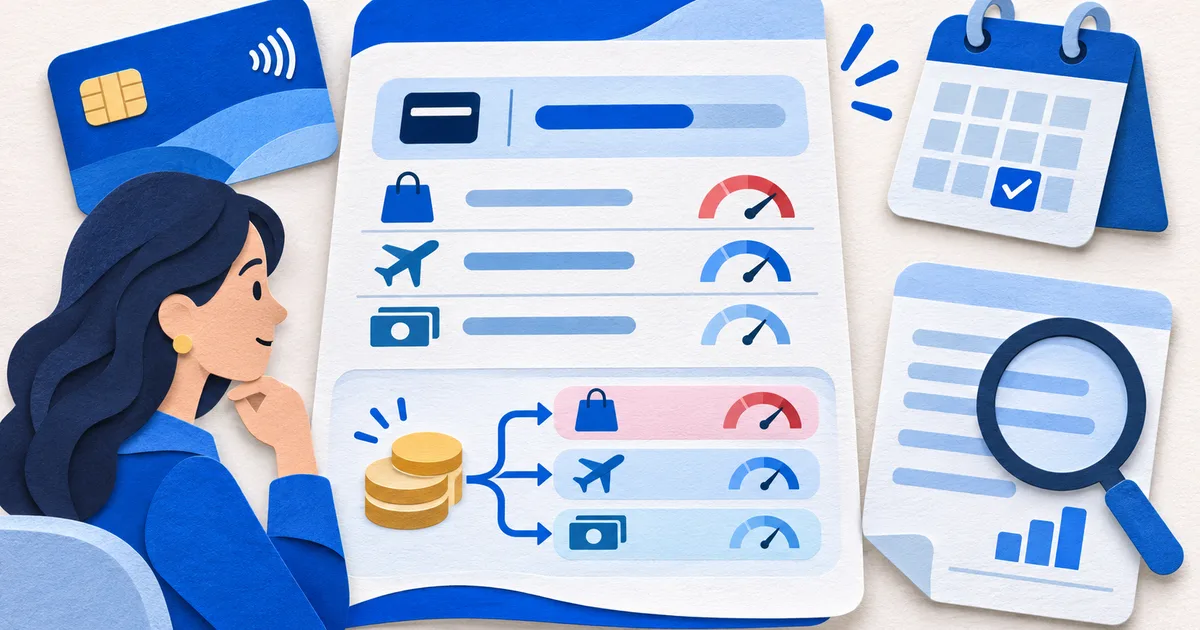
Payment allocation checks
List each balance category and the APR effective for the cycle.
Split the payment into minimum and above-minimum portions.
Apply the general rule only after checking for special plan terms.
Use the next statement to verify the issuer's actual allocation.
Request an allocation breakdown when category balances do not reconcile.
Worked example: a $375 payment across three balances
Assume a $75 minimum and $300 excess, with no special promotional allocation rule.
| Evidence or step | Value or event | How to read it |
|---|---|---|
| Cash advance | $200 at 29.99% | The first $200 of the excess can eliminate this highest-rate balance. |
| Purchases | $900 at 21.99% | The remaining $100 excess can reduce this next-highest rate. |
| Balance transfer | $1,500 at 0% | None of the $300 excess remains for this balance. |
| Minimum portion | $75 | Allocation depends on the agreement and applicable special rules. |
Build a balance-and-rate map
List every balance category shown on the statement: purchases, cash advances, transfers, deferred-interest promotions, installment plans, and any other separately disclosed balance. Record the APR, opening balance, new activity, payments or credits, and closing balance for each. A single total balance hides the allocation question.
Use the rate in effect for the relevant cycle, not an APR copied from a current web page. Promotions can expire and variable rates can change. If the statement groups two balances under one APR but the agreement treats them differently, keep the issuer's disclosed categories and add a note instead of inventing a split.
Separate the minimum from the excess
Suppose the minimum due is $75 and the cardholder pays $375. For allocation analysis, treat $75 as the minimum portion and $300 as the above-minimum portion. The federal highest-APR-first rule generally applies to the $300, while the issuer may allocate the $75 according to the card agreement, subject to special rules.
This distinction explains why subtracting the full $375 from the highest-rate balance can be wrong. It also explains why the highest-rate balance may fall by less than the payment even when no new transactions were added. Fees, interest, and later posting can further change the next statement's category balance.
Order the balances by APR
Rank the applicable balances from highest APR to lowest. Apply the excess payment to the highest-rate balance until it is exhausted, then move any remaining excess to the next rate. Keep zero-percent promotions in the map even though they are likely to receive excess only after higher-rate balances, unless a special rule changes the order.
Do not rank by dollar balance, transaction age, or category name unless the agreement or a specific rule requires it. A small cash-advance balance at 29.99% can receive excess payment before a much larger purchase balance at 21.99%. Your calculation is a prediction until the issuer posts the payment and discloses the next cycle.
Recognize special situations
Deferred-interest balances can have special allocation rules, particularly near the end of a promotion. Required payment plans and secured arrangements may also be treated under specific provisions. Regulation Z contains exceptions, so a generic highest-rate rule should not be applied blindly to every plan shown on a statement.
When a promotion is close to expiration, read the promotional terms and contact the issuer for a payoff or allocation explanation. Record the response date and representative or message reference. The statement can show the outcome, but it may not contain every contractual instruction that produced it.
Reconcile the next statement
Start with each prior closing balance, add new transactions, fees, and interest, subtract credits and the allocated payment, and compare with the new balance category. Do not assume the payment was effective on the day it was initiated; use the posted or credited date supported by the issuer record.
If the categories do not reconcile, check whether the issuer displays an average daily balance rather than a closing balance in its interest table. Also check for transfers between categories, promotional expirations, reversed payments, and fees assigned to a cash-advance or purchase balance. Ask for a transaction-level allocation breakdown when the variance is material.
Avoid misleading payoff conclusions
Payment allocation affects interest, but a statement review should not claim that a particular payment strategy is universally optimal. The cardholder may face cash-flow needs, due dates on other accounts, expiring promotions, or contractual constraints that are outside one statement. Present the observed rates and allocation mechanics clearly.
A useful analysis reports what the statement shows, a rule-based expected allocation, the next statement's actual category movements, and any unresolved difference. That gives the user evidence for a conversation with the issuer without replacing the card agreement or personalized financial advice.
When documenting the result, preserve the payment confirmation and both surrounding statements. State whether the allocation is confirmed, estimated, or still awaiting the next cycle. That simple status label prevents a projected highest-rate allocation from being reused later as though it were an issuer-posted fact.
Official sources used for this page
These sources explain federal consumer rules or common contract terminology. Your own card agreement and issuer records control account-specific rates, classifications, deadlines, and decisions.