
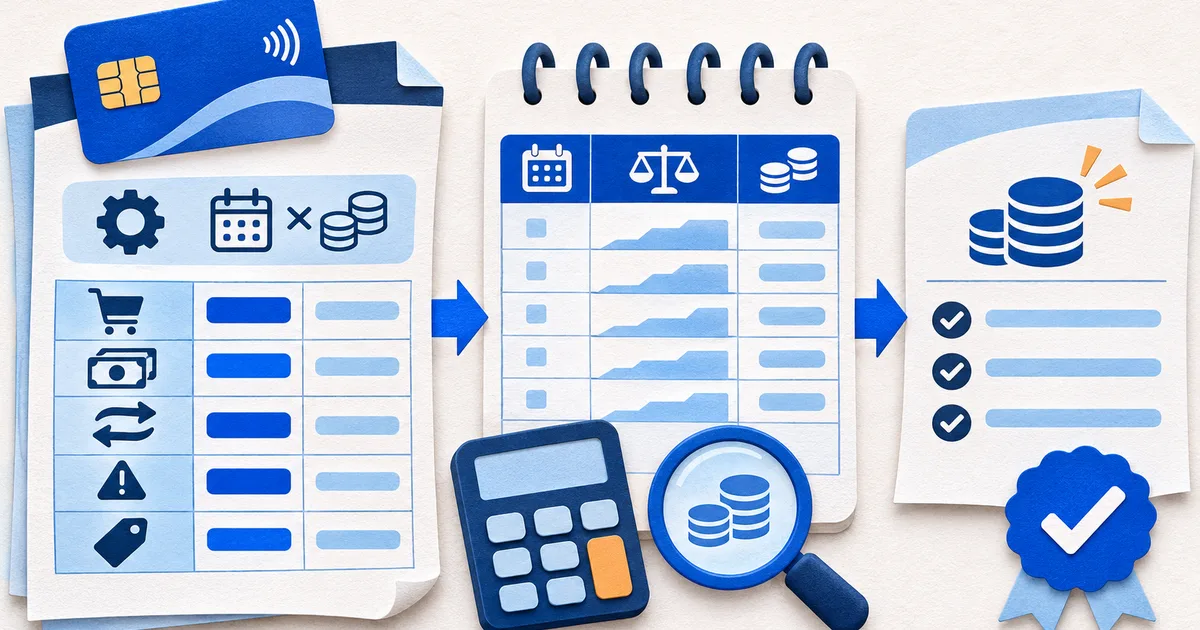
Inventory the categories
Record each APR, balance subject to interest, finance charge, promotional expiry, and cycle length.
Note variable-rate language, penalty rates, and grace-period status.
Rebuild balance movement
Begin with each category's opening balance and apply transactions, payments, credits, fees, and adjustments on their effective dates.
If only average daily balance is shown, preserve it and state that a complete daily path is unavailable.
Apply the periodic rate
Convert APR using the disclosed daily or periodic convention and apply it to the relevant balance for each day.
Keep calculation precision until the issuer's stated rounding point.
Build an interest workpaper
Separate the source inputs, calculation steps, comparison result, and every unresolved difference.
Terms
APR, category, method, days, and grace status.
Events
Date, debit, credit, payment, and balance.
Rate
Annual conversion and precision.
Result
Estimate and issuer charge by category.
Variance
Amount, likely cause, request, and resolution.
Compare by category
Match estimates with the finance charge for each balance class, then investigate timing, residual interest, fees, and rounding.
Do not insert an unexplained plug to make the worksheet agree.
Keep the estimate bounded
The workpaper can test reasonableness but does not replace the issuer's system or agreement.
For a dispute, preserve statement, terms, worksheet, variance, and issuer response.
Start with one balance class, such as purchases, and record its APR, grace-period status, balance subject to interest, cycle days, finance charge, and disclosed method. Do not mix cash advances, transfers, promotions, or penalty-rate balances into the same estimate. Each category can have a different start date, rate, payment allocation, or absence of a grace period.
Build the daily path from opening category balance and effective dates of posted purchases, payments, credits, fees, and adjustments. If the statement provides only an average daily balance, preserve that issuer figure and state that the full path cannot be independently reproduced from the page. Do not invent event dates or distribute a closing balance evenly across the cycle.
As a bounded check, a 1,200 balance held ten days at 24 percent APR has a simple estimate of 1,200 multiplied by 0.24 divided by 365 and then by 10, or about 7.89 before issuer rounding or compounding. This tests scale only. Compare the exact account convention, denominator, precision, and method before extending the estimate.