
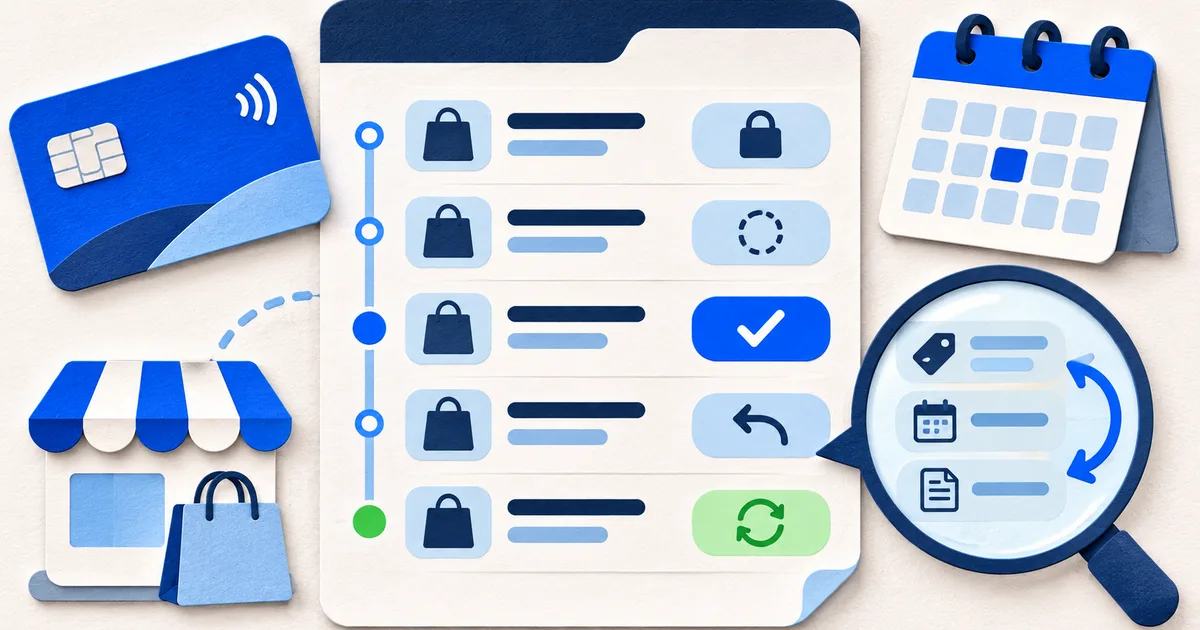
Authorization creates a hold
The merchant requests approval and the issuer may reduce available credit by an estimate.
Hotels, fuel, rentals, and restaurants can authorize an amount different from the final purchase.
Track one transaction through settlement
Capture observations from the changing account view.
Authorized
Time, pending amount, descriptor, and credit effect.
Adjusted
Tip, deposit, partial capture, or release.
Posted
Final amount, date, reference, and cycle.
Matched
Evidence that both views are one event.
Resolved
Accepted, corrected, disputed, or expired.
Pending activity can change
The merchant may complete, adjust, cancel, or never settle the authorization.
The pending descriptor can name a processor or location that differs from the final row.
Settlement creates the posted row
After settlement, the issuer records the final amount and posting date used for statement inclusion.
Transaction date may stay earlier, so retain both dates where available.
Overlap can mimic duplication
A hold and its settlement can appear together temporarily. Compare amount, merchant clues, date, and reference.
Two posted rows require a different review from one pending and one posted appearance.
Act according to status
Ask about an estimated pending amount before treating it as final; use the issuer's official review route for an unfamiliar posted charge.
Record observation time, contact, case reference, and outcome without publishing card data.
Imagine a restaurant places a 60 authorization before the tip is finalized. The account shows a pending 60 hold, then a posted 72 transaction, with a short overlap where both are visible. Record observation times, descriptors, amounts, and state. The two appearances may represent one purchase, so do not count 132 or call it a duplicate before settlement evidence is clear.
A pending authorization can be adjusted, partially captured, cancelled, or allowed to expire. Hotels, fuel stations, transit, rentals, and restaurants often use estimates. Merchant wording can change between authorization and posting, and the transaction date can precede posting by several days. Pending duration varies, so use account-specific guidance before labeling a delay as an error.
The posted row is the settled account event normally used for statement-cycle inclusion. Link it to the earlier hold through merchant clues, amount path, date, card suffix, and reference where available. Preserve both observations if the timing matters, but keep the hold outside the issued ledger and interest calculation until the issuer records a posted event under its rules.