How to Investigate an Unfamiliar Credit Card Charge
An unfamiliar descriptor is not proof of fraud, but it deserves a prompt evidence-led review that does not expose the card number.
Incident lab: investigate a merchant name you do not recognize
Use contact information from a known receipt or independently verified site if merchant contact is appropriate. Never rely only on a telephone number embedded in a suspicious descriptor. If the posted charge remains unfamiliar or unauthorized, contact the issuer through the official app, known site, or number on the card and follow its instructions and timing requirements.
Track case number, contacts, card restriction or replacement, requested evidence, provisional credit, deadlines, decision, and later statement treatment. Review subsequent cycles for related charges, reversed credits, fees, or interest. Preserve the original row and final outcome together. This creates a useful incident record without claiming that the website can determine fraud.
If the issuer replaces the card, update legitimate merchants through trusted account channels and watch for recurring charges that migrate automatically or fail. Card replacement does not prove every future charge is authorized, and it may not stop all merchant tokens. Record issuer instructions and review the next statements without distributing the new card number in support messages.
Separate recognition from dispute rights. A charge can be recognized but have the wrong amount, duplicate settlement, undelivered goods, or failed cancellation. Preserve the exact problem and merchant evidence, then follow the issuer's applicable route. Do not label every disagreement fraud or let a recognized merchant name close a valid billing issue.
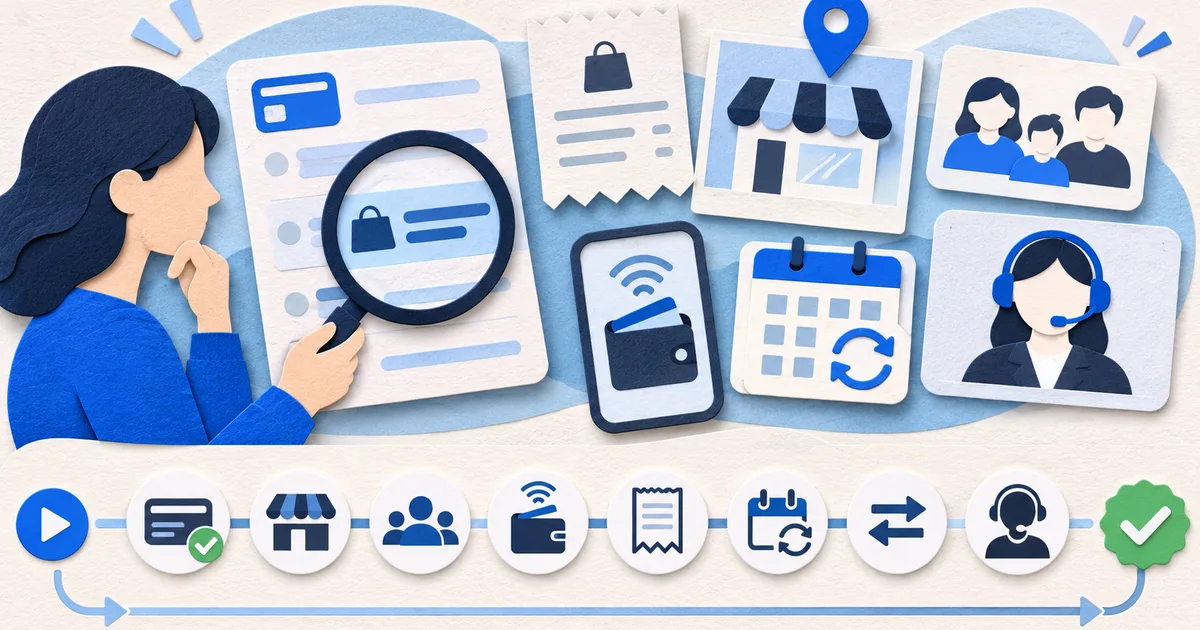
Use an incident checklist that is quick enough for urgent review but preserves uncertainty. It should capture the row, ordinary searches, authorized-user response, merchant evidence, issuer contact, protection action, deadlines, and outcome. Mark unperformed checks rather than assuming them. A concise chronological file is more useful than a long narrative because the cardholder and issuer can see what is known, what was ruled out, and what must happen next.
Do not delay issuer contact solely to complete every private search when the card terms or risk warrant prompt action. Preserve what has already been checked and use the issuer's official guidance for next steps. Further merchant research can continue without exposing credentials, but deadlines and security controls should not depend on a perfect merchant identity.
First establish whether the row is final by checking the pending versus posted transaction guide and preserve the exact settled descriptor.
Use the credit card statement analyzer to organize the row and supporting evidence, then contact the issuer through an authenticated channel when required.