How to Trace a Missing Credit Card Statement Transaction

An expected transaction may be pending, posted in another cycle, settled under different wording, reversed, placed on another card, or never completed.

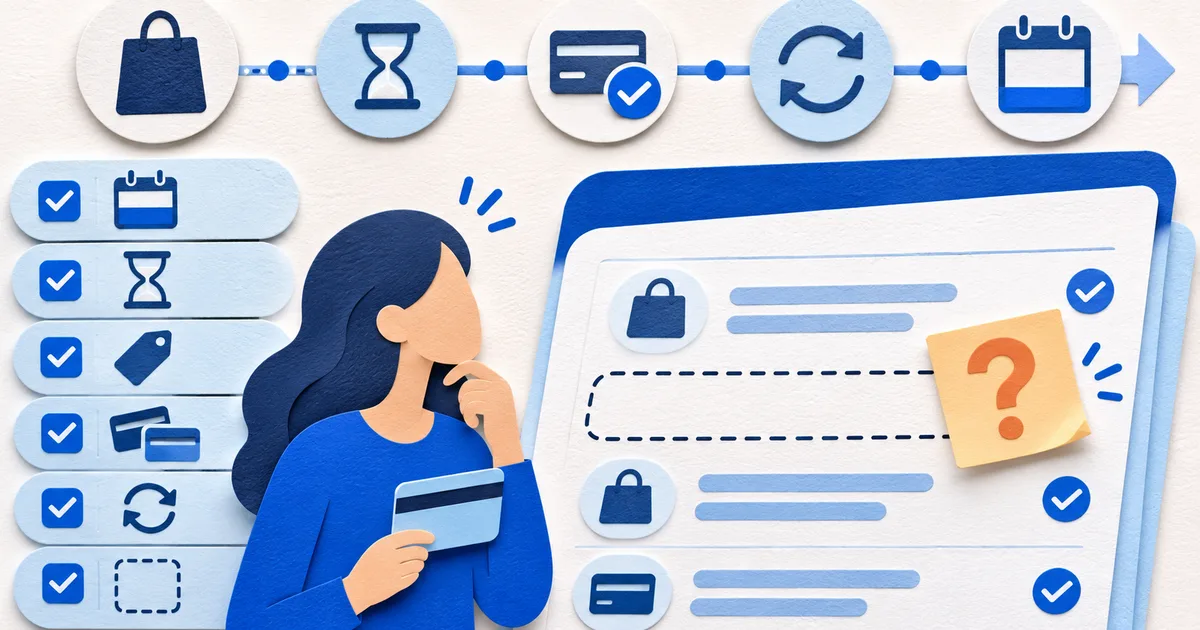
Fictional bank transaction timeline tracing an expected payment through pending, posting, reversal, and statement cutoff states
Original editorial artwork for this guide. Any depicted account details are fictional.

Define the expected event

Create a missing-transaction trace

Follow one expected event across every possible state and record.

Event identity

Time, amount, currency, merchant, card suffix, and confirmation.

Cycle test

Expected statement, closing date, and adjacent statement search.

Status history

Authorized, pending, posted, reversed, released, or refunded.

Alternative row

Different descriptor, converted amount, account, or user.

Closure evidence

Final row, release, refund, or official explanation.

Check the billing-cycle boundary

Search descriptor and account variations

Test reversal and noncompletion

Escalate with a complete trace

Missing-row lab: locate the layer where the event disappeared

Inspect the balance sequence around where the row should appear. If the balance moves by the expected value without a separate line, test combined rows, netted presentation, carried totals, or a differently described transaction. If movement never appears, the event may be outside the period or never settled. Arithmetic narrows the question but cannot create missing source evidence.

Verify page count, sequence, text extraction, wrapped lines, and any spreadsheet filters. A transaction can exist in the PDF yet vanish during OCR or import. Search the original page rather than only a normalized merchant field, and compare row counts and totals. Preserve the source file before repairing, splitting, decrypting, or re-exporting a working copy.

If the expected posting window has passed, ask the merchant or issuer through a verified route and retain the response. Record case, explanation, corrected statement if any, and final account state. Close with found in another cycle, pending, reversed, extraction error, different account, issuer correction, or unresolved status. Never manufacture a row to make another ledger balance.

When another ledger contains the expected item, preserve that entry but do not force a match. Compare account, direction, reference, amount, currency, and cutoff. The ledger may be early, duplicated, or assigned to the wrong card. Record the proposed relationship and await issuer or merchant evidence. Reconciliation is stronger when an unmatched item stays open than when a convenient row is manufactured.

If the missing item affects a payment, dispute, bookkeeping close, or tax record, state that downstream consequence in the exception. A low-value row can still be material because it proves a deadline or recurring agreement. Assign priority from the decision, not only the amount. Close the affected report only when the row is found, the source explains its absence, or the limitation is explicitly accepted by the responsible reviewer.

A date near the cycle boundary should be tested with the transaction date versus posting date guide before the row is classified as missing.

If the absent event explains a balance gap, continue with why a credit card statement balance does not match and keep the variance open until source evidence resolves it.

After checking adjacent cycles and settlement state, record the unresolved row in the credit card statement analyzer instead of adding a balancing entry without source support.

Continue this evidence trail with How to Fix a Credit Card Statement PDF Upload. Upload failure can come from the file, browser, connection, or service limits. Test one cause at a time without weakening privacy.

Continue with a statement review

Apply the checks with the missing transaction review tool while keeping the issuer document as the control record.

Open the related tool