
Name both figures precisely
Write down whether each number is a previous balance, statement balance, current balance, available credit, payoff amount, bookkeeping balance, or spreadsheet total. These figures follow different rules and should not be treated as synonyms.
Start from the earlier verified balance
Use the older source as the bridge opening. If it is the statement balance, begin at cycle close. If it is a bookkeeping value, confirm that all activity through its ledger date has already been recorded.
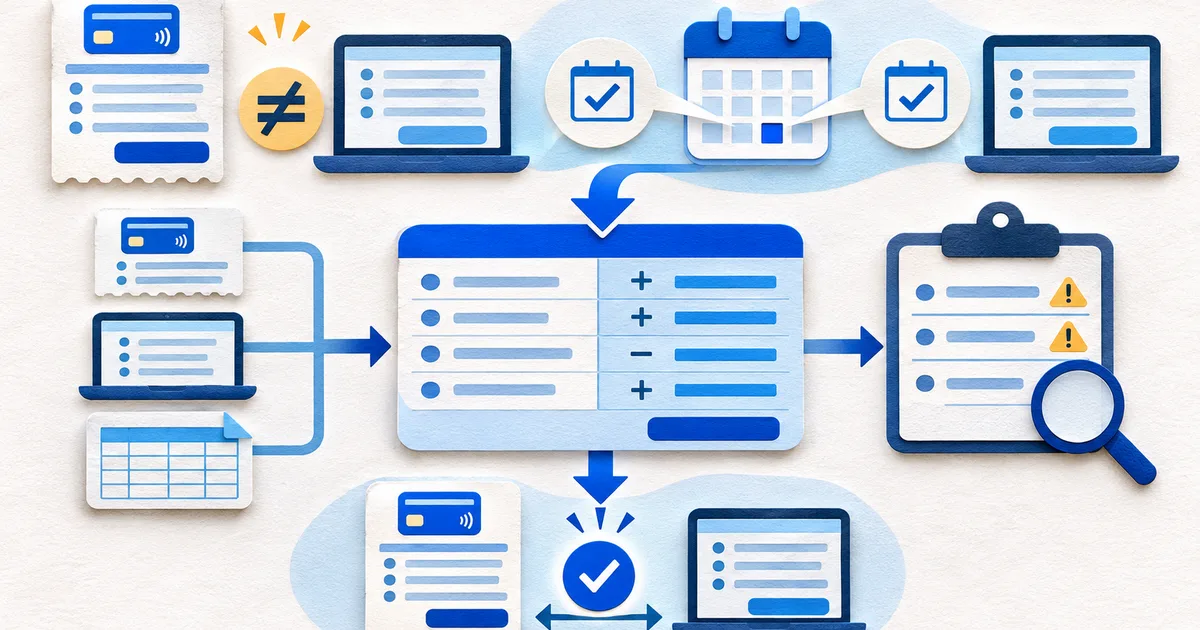
Create a balance mismatch bridge
Use one line per event between the two dated balances.
Opening point
Identify the older balance and exact cutoff.
Posted additions
List purchases, fees, interest, advances, and transfers.
Posted reductions
List payments, refunds, chargebacks, and credits.
Timing schedule
Keep pending and processing items separate.
Residual case
Assign evidence and a next step to the remaining difference.
Apply intervening posted activity once
Add purchases, advances, fees, interest, and other debits posted after the first cutoff. Subtract payments, refunds, chargebacks, rewards credits, and other credits posted in the same interval.
Keep timing states outside the posted bridge
List pending authorizations, payment instructions still processing, disputed amounts, and temporary credits in a separate schedule. Explain how the issuer presents each state without pretending it has posted.
Investigate the residual instead of plugging it
A remaining difference can point to an omitted row, wrong sign, foreign conversion, returned payment, balance transfer, installment plan, corrected statement, or activity on another card account. Test each explanation from source evidence.