Transaction Date vs Posting Date on a Credit Card Statement

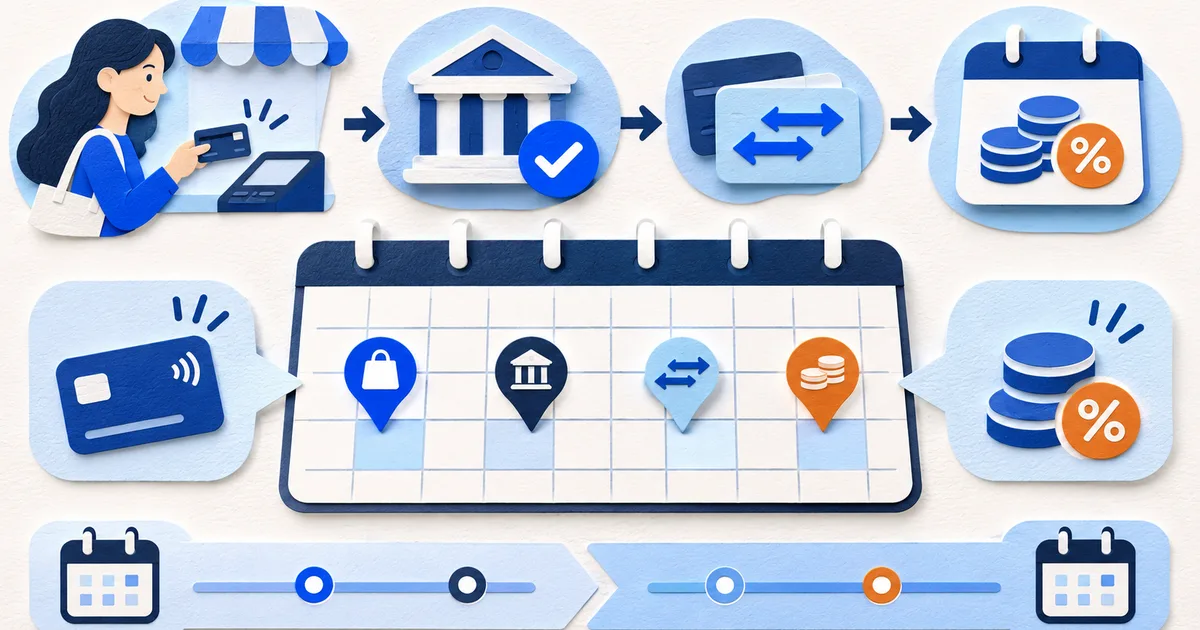
The transaction date usually marks when activity began; the posting date records when the issuer entered the settled event on the account.

Calendar and fictional row distinguishing transaction, posting, settlement, and value dates
Original editorial artwork for this guide. Any depicted account details are fictional.

The purchase begins

The transaction date often reflects the merchant interaction or authorization request.

Time zones, offline terminals, and batch practices can shift the displayed date.

Settlement follows

The merchant or processor submits a final transaction after authorization. Tips, weekends, travel, and delayed fulfilment can extend the gap.

A long gap is a clue, not automatic proof of error; compare receipts and merchant records.

Keep a transaction date trail

One event may require several timestamps.

Initiated

Purchase date, time zone, and receipt.

Pending

Amount, descriptor, and observation time.

Posted

Final amount, date, and statement cycle.

Corrected

Refund, reversal, dispute, or adjustment.

Applied

Date field used in the report and why.

The issuer posts the row

The posting date is when the issuer records the settled debit or credit and commonly determines statement-cycle inclusion.

A purchase before closing can appear on the next statement if it settles after cutoff.

Corrections get their own dates

Refunds, reversals, and chargebacks are new events and should link to the purchase without overwriting it.

Foreign conversion can use another network or processing date, depending on issuer disclosures.

Choose by purpose

Transaction date helps receipt matching; posting date supports statement reconciliation; other reporting uses the applicable rule.

State which field a report uses because silent date mixing creates duplicates and missing-period results.

Imagine a hotel authorization on June 28, final checkout on June 30, merchant settlement on July 2, and issuer posting on July 3. The transaction date can reflect the stay or authorization, while the posted event belongs to the later statement under the issuer's cutoff. Keep each timestamp and state rather than forcing a single date to answer shopping, reconciliation, and accounting questions.

Pending amounts can change because of deposits, tips, partial capture, offline terminals, exchange rates, or merchant adjustments. Record observation time and pending descriptor if the changing account view matters, but do not insert a hold into the closed statement ledger. When the final row posts, link it to the earlier observation using merchant clues, amount path, reference, and evidence instead of assuming every similar value is the same event.

Refunds and reversals start new timelines. A return date, merchant processing date, issuer posting date, and statement cycle can all differ from the original purchase. Preserve both events and their connection. Overwriting the purchase date or deleting a net-zero pair removes evidence needed for cycle comparison, dispute history, and understanding temporary use of available credit.

Timeline lab: place one purchase in the right cycle

Choose the date field according to purpose and document that choice. Receipt matching usually begins with purchase time; issued-statement reconciliation uses posting and cycle inclusion; another accounting or tax decision follows its applicable method. A report that silently mixes fields can duplicate activity, omit boundary rows, or create false month-to-month changes even when every individual date is correct.

Build a transaction timeline with initiated, pending, adjusted, posted, credited, and disputed states as applicable. Include source, observation time, amount, currency, descriptor, confidence, and statement cycle. If an expected row remains absent after the normal posting window, verify filters and account scope, then ask the merchant or issuer through an official route rather than editing the statement to match memory.

Time zones deserve attention for travel, online merchants, and late-night purchases. A receipt can show local merchant time while the issuer processes in another zone and posts on a different calendar date. Preserve the visible times and zones where available. Do not use a one-day difference alone to conclude that either the receipt or statement is wrong.

When comparing periods, choose one date field consistently and disclose boundary exceptions. If analysis uses posting date, a late-settling purchase belongs to the later cycle even when the shopping occurred earlier. A separate behavioral view can use transaction date, but it should reconcile back to posted rows and identify events without reliable purchase dates.

Record the reporting consequence beside every boundary item. A charge can belong to the next issued statement, the earlier shopping-behavior period, and a different bookkeeping period under an applicable rule. Those classifications can coexist when labeled. Reconciliation should use the issuer's posting and cutoff evidence, while other views retain the chosen date and a link back to the posted row. This avoids forcing one calendar into every decision.

Keep sorting stable when two events share a date and no time is available. Do not invent intraday order from page position unless the issuer confirms that convention. Use source sequence as a retained reference and avoid claims about temporary balances that require an order the statement does not provide.

A row that falls outside the expected cycle can be traced with the missing statement transaction workflow using both event dates and the issuer's settled record.

For the terms surrounding those dates, consult the credit card statement glossary rather than assuming every issuer labels authorization and posting states identically.

The credit card statement analyzer preserves both dates when the issuer provides them, which keeps the cycle decision auditable.

The next closely related decision is covered in How to Review Credit Card Statement Fees and Interest. A card cost or adjustment should connect to a named event, disclosed rule, balance category, and place in the statement balance equation.

Continue with a statement review

Apply the checks with the timestamped card statement review while keeping the issuer document as the control record.

Open the related tool