How to Find Recurring Charges on Credit Card Statements

Recurring-charge detection produces candidates, not confirmed subscriptions. Compare several complete cycles and verify the service before acting.

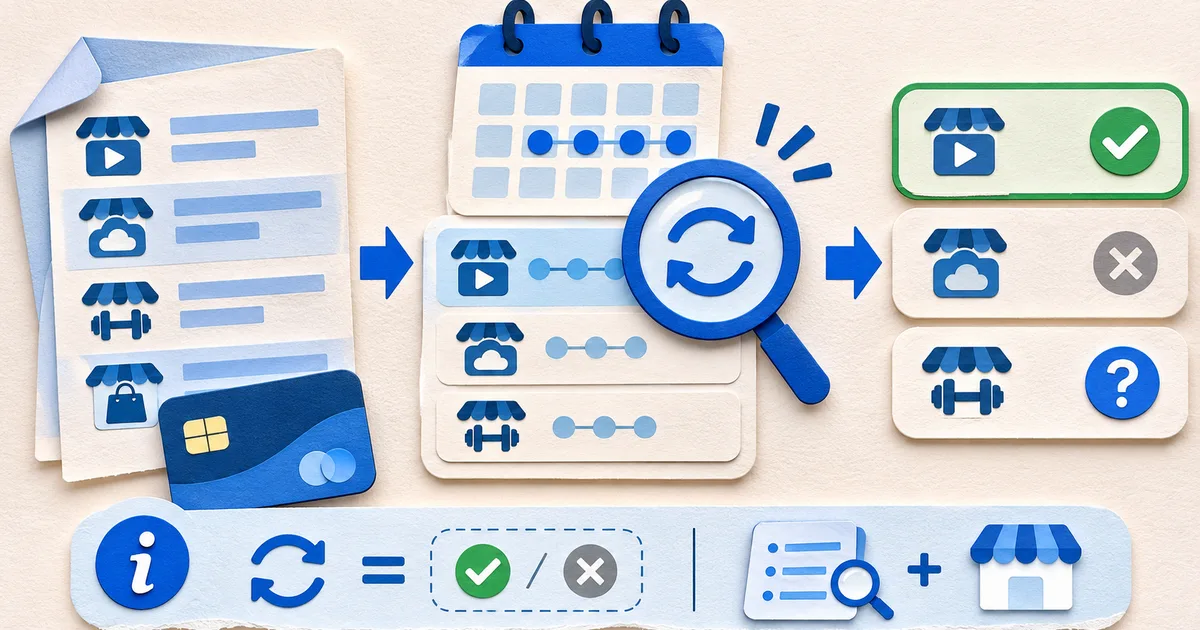
Fictional payment history with panels marking possible recurring patterns for confirmation
Original editorial artwork for this guide. Any depicted account details are fictional.

Collect comparable billing cycles

Normalize merchants without deleting source text

Build a recurrence evidence card

Give every candidate a visible basis and confirmation state.

Source rows

Keep each exact descriptor, amount, date, and statement cycle.

Merchant group

Document the normalization rule and conflicting possibilities.

Cadence

Calculate intervals and explain expected date movement.

Amount pattern

Record fixed, stepped, seasonal, or usage-based behavior.

Confirmation

Name owner, agreement evidence, current status, and next action.

Test interval and amount behavior

Verify ownership and current status

Turn candidates into a review queue

Pattern lab: test a changing monthly charge

Compare alternative explanations before confirmation. The pattern could be a subscription with a price increase, an installment, a monthly wallet-funded purchase, an account fee, or unrelated sellers sharing a processor. Direction, descriptor fragments, receipts, app-store history, merchant account records, authorized-user knowledge, and issuer references can strengthen or weaken each explanation. Equal values alone are particularly weak because many unrelated obligations repeat at round amounts.

Store a candidate record with every supporting row, observed cadence, amount range, first and latest occurrence, skipped-period tolerance, confidence, next expected window, and confirmation status. Keep refunds and reversals linked rather than removing them. A refunded monthly service still demonstrates a billed event, while a reversed authorization that never settled should not be treated like a completed recurring charge.

Only a trusted merchant, contract, invoice, app account, or issuer record should move the status from candidate to confirmed. Record whether the charge is recognized, active, cancelled, disputed, or unknown, plus the date and source of that finding. Do not recommend cancellation from pattern shape alone; the safe next step depends on ownership, terms, and current billing status.

Annual and quarterly candidates need longer coverage than monthly ones. A twelve-month span can still miss a delayed annual renewal, while two charges one year apart provide only a weak cadence estimate. State the covered cycles and missing periods beside every result. If account history is incomplete, say that recurrence could be underdetected instead of presenting an absence of matches as evidence that no recurring charge exists.

After a cancellation, monitor the next expected window and keep the cancellation confirmation. A merchant credit may arrive after the last debit, and a new descriptor may appear after a billing-platform change. Close the candidate only when the expected charge does not post or when the merchant and issuer records show the final outcome. This follow-through turns a detection list into a useful review process.

If several names may represent the same merchant, decode them with the credit card descriptor review guide before grouping a series.

Rank candidate series across cycles with the credit card recurring charge finder and verify authorization and cancellation status separately.

The next closely related decision is covered in How to Decode Credit Card Transaction Descriptions. A descriptor is a compact routing label, not a receipt. Decode its parts while keeping facts and inferences separate.

Continue with a statement review

When the evidence is ready, use the recurring credit card charge finder while keeping the issuer document as the control record.

Open the related tool