
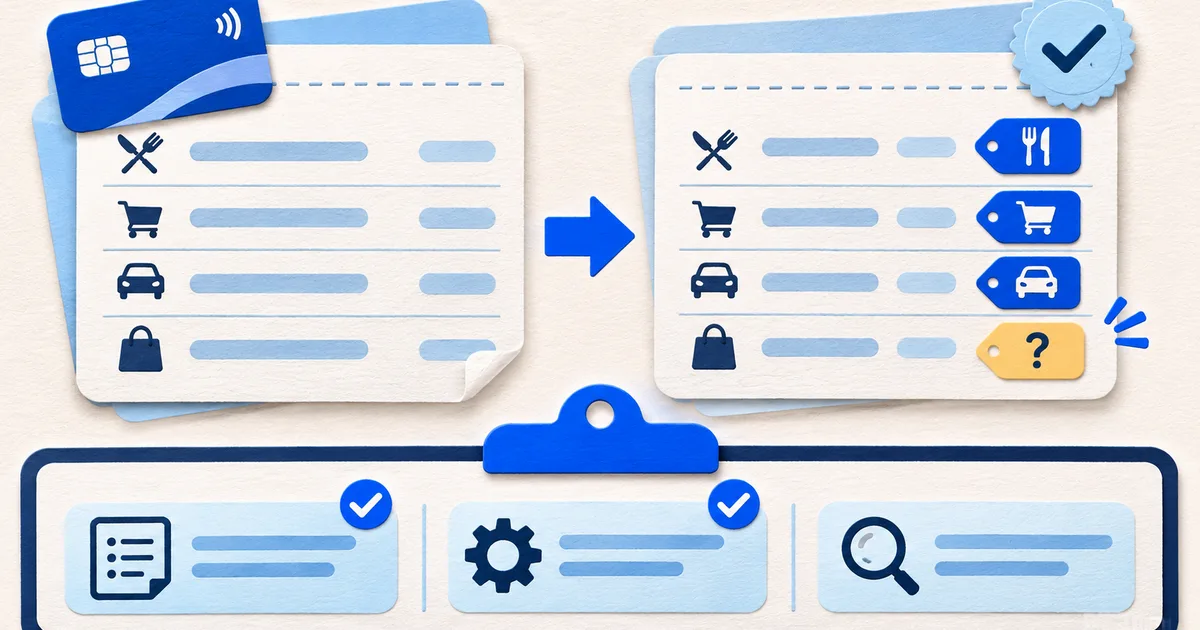
Build a category decision log
Record the rule beside the exceptions so another reviewer can apply it the same way.
Category
Define the category in one sentence and state its purpose.
Positive rule
Describe the evidence that permits an assignment.
Exclusions
List transaction types and merchant cases that must not use the rule.
Confidence
Set the result state when evidence is incomplete.
Example
Keep one confirmed row and one difficult counterexample.
Define what the categories are meant to answer
A personal spending view, bookkeeping ledger, subscription review, and tax workpaper need different classifications. Write the decision first, then choose a category set that supports it.
Keep the list short enough to apply consistently. Add subcategories only when they change a real decision or make a material group easier to review.
Preserve the issuer row before adding interpretation
Retain posting date, exact descriptor, amount, currency, card suffix when shown, and source page. Put normalized merchant, category, owner, purpose, and confidence in separate fields.
This two-layer design allows a corrected category or merchant name without altering what the issuer printed. It also supports later dispute or reconciliation work.
Write rules for difficult transaction types
Decide how to handle refunds, reversals, cash advances, balance transfers, fees, interest, rewards credits, and payments before running totals. These entries should not be forced into ordinary purchase categories.
For mixed merchant purchases, either retain a mixed category or split the amount only when item-level evidence supports the allocation. A store name does not prove the contents of the basket.
Use confidence and review states
Mark a category as confirmed, rule-assigned, suggested, or unresolved. Record the rule or evidence behind any automated assignment rather than presenting every label as equally certain.
Review large, unfamiliar, first-time, cash-like, foreign, and ambiguous charges before publishing a category summary. Material uncertainty should remain visible in totals that depend on it.
Test the rules against a fresh cycle
Apply the same rules to a later complete statement and measure how many rows require manual correction. A rule that repeatedly sends different purchases into one broad bucket may not be useful.
Version the category dictionary when definitions change. Reclassify earlier periods only when a comparison requires consistent treatment and retain a record of the change.
Take a descriptor that often belongs to a grocery marketplace but can also represent restaurant delivery, pharmacy products, tips, or a membership fee. Preserve the raw issuer text and define the review purpose first. A personal spending view may need groceries and dining separated; bookkeeping or tax work may require a different classification system. Never force one label to perform all three jobs.