
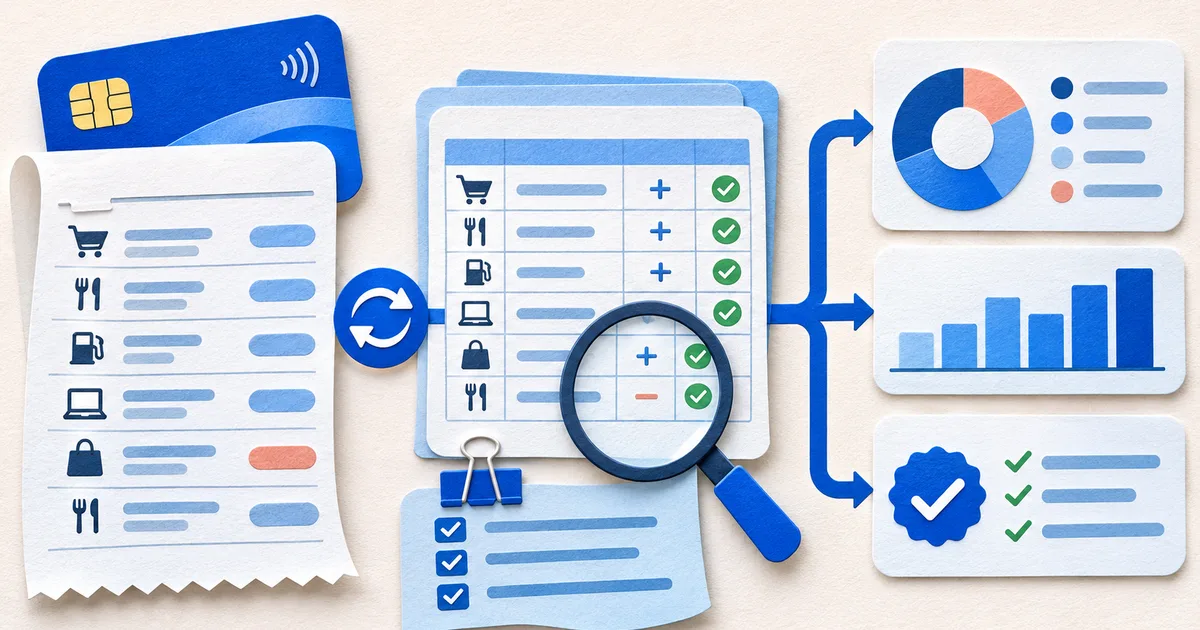
Prove that the source is the intended statement
Confirm cardholder, masked card reference, issuer, currency, billing-cycle dates, page sequence, and document version. A correct extraction from the wrong cycle is still the wrong analysis.
Locate the previous balance, new balance, payment box, activity sections, fee summary, interest summary, and rate table before focusing on individual merchants.
Assemble a statement analysis release note
Pair the output with a compact record of what passed and what remains provisional.
Source scope
List account suffix, cycle dates, pages, currency, and document version.
Ledger control
Record row count and the balance-reconciliation difference.
Corrections
List every changed field with its reason and page reference.
Interpretations
Count suggested merchants, categories, and recurring candidates by confidence.
Open effects
Name unresolved fields and every total or chart they can change.
Create one row for each posted event
Capture the issuer description, posting date, transaction date when supplied, amount, direction, currency, page, and balance category. Do not merge similar charges or erase repeated rows during extraction.
Store corrected values beside the extracted values with a reason and source reference. An unreadable digit should become an exception, not a guess made from nearby activity.
Rebuild the card balance
Starting with the previous balance, add purchases, cash advances, transfers, fees, and interest, then subtract payments, refunds, chargebacks, and other credits. Follow the issuer's signs and section totals.
Compare the result with the printed new balance. Investigate duplicated rows, missing continuation pages, wrong signs, and separately presented adjustments before releasing a summary.
Add interpretations as separate fields
Normalize merchants, suggest categories, group possible recurring charges, and identify unusual activity only after preserving the source row. Add a confidence state and the rule or evidence used.
A merchant pattern can support a review queue but cannot prove authorization, subscription status, ownership, or business purpose. Keep those conclusions outside the extracted fact layer.
Release findings with explicit boundaries
Report the number of source rows, reconciled rows, unresolved values, manual corrections, suggested categories, and recurring candidates. Name every output affected by an open item.
State the card accounts and cycles included. Trends, affordability conclusions, credit-score predictions, and legal determinations require evidence beyond one statement analysis.
Imagine a six-page card statement whose payment summary and 83 transaction rows are readable, but one foreign-currency amount is blurred. Begin the release note with exact scope: masked card, currency, opening and closing dates, expected pages, captured rows, and fields that could not be approved. That inventory lets another reviewer distinguish a nearly complete dataset from a complete-looking file that silently guessed a value.