How to Decode Credit Card Transaction Descriptions

A descriptor is a compact routing label, not a receipt. Decode its parts while keeping facts and inferences separate.

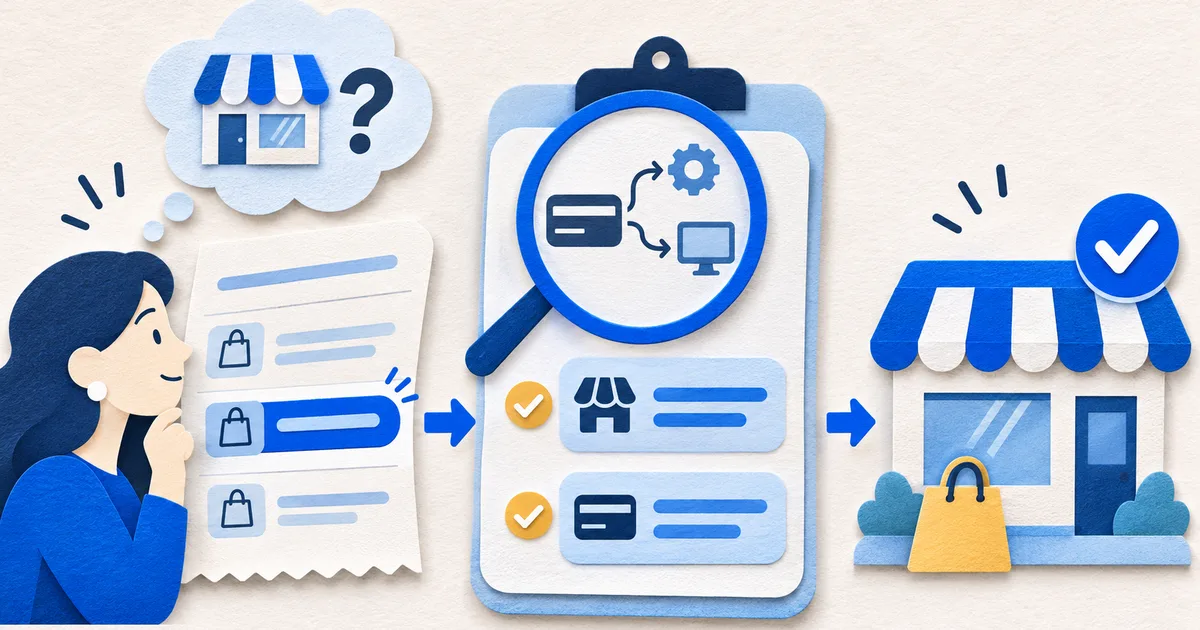
Review notes breaking fictional transaction descriptions into merchant and payment clues
Original editorial artwork for this guide. Any depicted account details are fictional.

Preserve the raw string

Copy spacing, abbreviations, telephone fragments, location codes, symbols, and references before cleaning the text.

Keep amount, currency, dates, suffix, and page beside it. A detached descriptor is easy to misidentify.

Separate processor from seller

Wallets, marketplaces, and payment facilitators may lead the text while the seller appears later or not at all.

Store any normalized merchant in a new field and retain the unchanged source label.

Treat geography as a clue

A city can identify a head office, terminal owner, or processor rather than the purchase location.

Online, recurring, card-present, and wallet markers can guide a search but need confirmation from receipts or account history.

Build a descriptor evidence card

Interpret the row without overwriting it.

Raw row

Exact text and full statement context.

Clues

Processor, possible seller, channel, and location.

Support

Receipt, order, wallet record, or issuer detail.

Confidence

Confirmed, supported, tentative, or unresolved.

Action

Accept, ask, recategorize, or contact issuer.

Assign confidence honestly

Call a match confirmed when a receipt or order agrees, supported when several independent clues agree, and unresolved when only the name resembles a brand.

Confidence labels focus manual review without converting a guess into a fact.

Escalate unfamiliar activity

Check other authorized users, subscriptions, and merchant aliases without publishing the full description.

If a posted charge remains unfamiliar, contact the issuer through its official app, site, or card number and keep the case reference.

Start with a fictional row such as PAYFAC STARLIGHT 4837 SEATTLE. Preserve the complete string, amount, currency, both available dates, card suffix, page, and direction. PAYFAC may describe a facilitator, STARLIGHT may be a seller fragment or parent company, 4837 may be a terminal or reference, and the city may belong to processing rather than the shopping location. None of those fragments alone proves what was purchased.

Parse the row into separate clues without changing the source: possible processor, possible seller, channel, geographic fragment, reference, and confidence. Search personal receipts, order email, wallet history, marketplace records, and authorized-user activity by amount and date. Store a cleaned merchant only in another field and cite the record that supports it. A matching brand name with the wrong value or timing remains an unconfirmed candidate.

Descriptor lab: move from raw text to a supported merchant

Intermediaries require special care. One wallet descriptor can cover many sellers, and one marketplace can carry goods, subscriptions, refunds, tips, and fees. Normalize in layers so a processor match does not automatically produce a seller or purchase category. If only the facilitator is known, keep purpose and category unresolved. This prevents a stable prefix from creating confident but false classifications across an entire statement history.

Protect reference details during research. Compare only the fragment needed to connect the row with a receipt or issuer trace, and mask the rest in shared notes. Do not post the full descriptor, card suffix, amount, and date on a public forum. When merchant contact is appropriate, use details from a known receipt or independently verified site rather than a telephone number that appears only in a suspicious transaction string.

Close the interpretation with one of four statuses: confirmed by direct support, supported by several independent clues, tentative from limited evidence, or unresolved. Record who reviewed it, when, and which source changed the status. If authorization remains in doubt after ordinary checks, use the issuer's official reporting channel promptly and preserve its case instructions. A useful descriptor file shows the reasoning without turning that reasoning into original statement evidence.

Test learned aliases over time rather than applying them forever. Merchants change processors, franchisees, trading names, and statement text, while the same facilitator serves unrelated sellers. Record the confirmed examples supporting an alias and define when new wording returns to review. A local alias table should improve search without erasing the raw string or bypassing evidence for a materially different row.

When the descriptor affects a consequential dispute, accounting entry, or disclosure, ask what level of identity the task truly needs. A processor match may be enough to locate an order but insufficient to identify the supplier. State the supported layer and retain uncertainty. That boundary is more useful than a polished merchant name that another reviewer cannot reproduce from the available records.

Processor prefixes and issuer codes can be checked against the credit card statement abbreviation guide without replacing the original descriptor in the evidence record.

If the same normalized merchant appears on several cycles, inspect it with the recurring payment review tool and keep the proposed merchant identity separate from the printed text.

A useful companion workflow is Credit Card Merchants, Categories, and Recurring Charges learning path, where the complete set of decisions and controls is organized together.

Continue with a statement review

For a source-linked working pass, open the statement recurring-payment finder and leave every uncertain field visibly unresolved.

Open the related tool