
How to Check Credit Card Statement OCR Results
OCR is ready only when the extracted values can be traced to the same pages, fields, signs, and totals in the issuer's statement.
This reader reconstructs card-statement fields from a scan or photograph, then marks the cells that the image cannot support confidently. A clean issuer PDF is preferable whenever one is available.
PDF or image · page-level checks
Your statement is being secured before analysis begins.
Leave this window open; your private results will load here when ready.
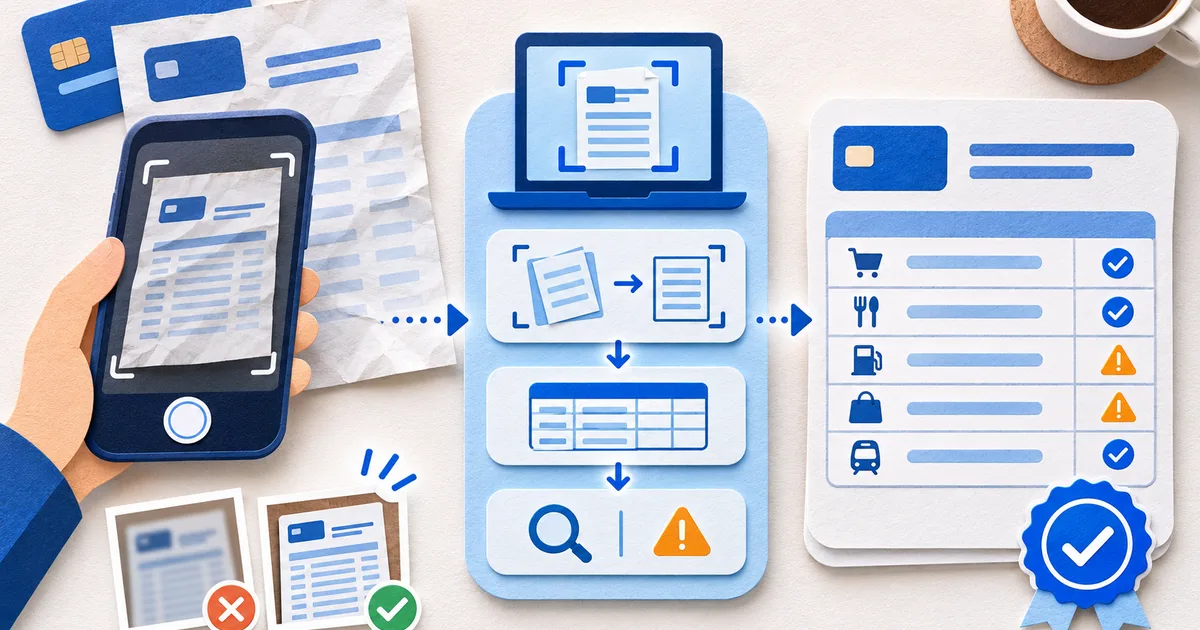
Visible boundaries prove page coverage; sharp aligned columns prevent dates, decimals, signs, descriptors, and balances from bleeding into one another.
Obtain the issuer's digital PDF when possible. A better source is safer than a long chain of image corrections.
Every page edge, page number, header, and amount column should be visible, level, and free from glare. Upload pages in their issued order.
A high-resolution image cannot repair a folded digit, cropped footer, or reflection over a minus sign.
Dates, decimal points, sign conventions, wrapped descriptors, and repeated headers create different OCR failure patterns.
Compare the most consequential fields and every low-confidence cell with the image rather than trusting a plausible value.
The row description and date are readable, but glare covers the final digits of a refund. The reader leaves the value unresolved rather than copying a nearby amount.
A new scan or the issuer PDF is needed before the row can enter totals.
Count reconstructed rows by page and test available balance movement across the sequence.
If a page or value is unreadable, keep the exception open and obtain a better source instead of completing it from nearby patterns.
Record source type, page count, capture date, orientation fixes, unreadable regions, and whether a cleaner issuer PDF was requested. For each critical correction, keep the page and field reference without copying unnecessary account data into ordinary notes.
Release extracted rows only for the uses their evidence supports. One uncertain merchant label may not prevent balance review, while an unreadable amount can invalidate totals and category results. Keep that release decision dated.
OCR is ready only when the extracted values can be traced to the same pages, fields, signs, and totals in the issuer's statement.
Protecting a card statement means controlling the entire copy lifecycle, not only hiding the account number before it is shared.
Begin with a card-specific evidence ledger that reproduces the statement balance. Interpret merchants, categories, and recurring patterns only after that control passes.
Page coverage, OCR, row reconstruction, balance checks, and human approval serve different roles.