
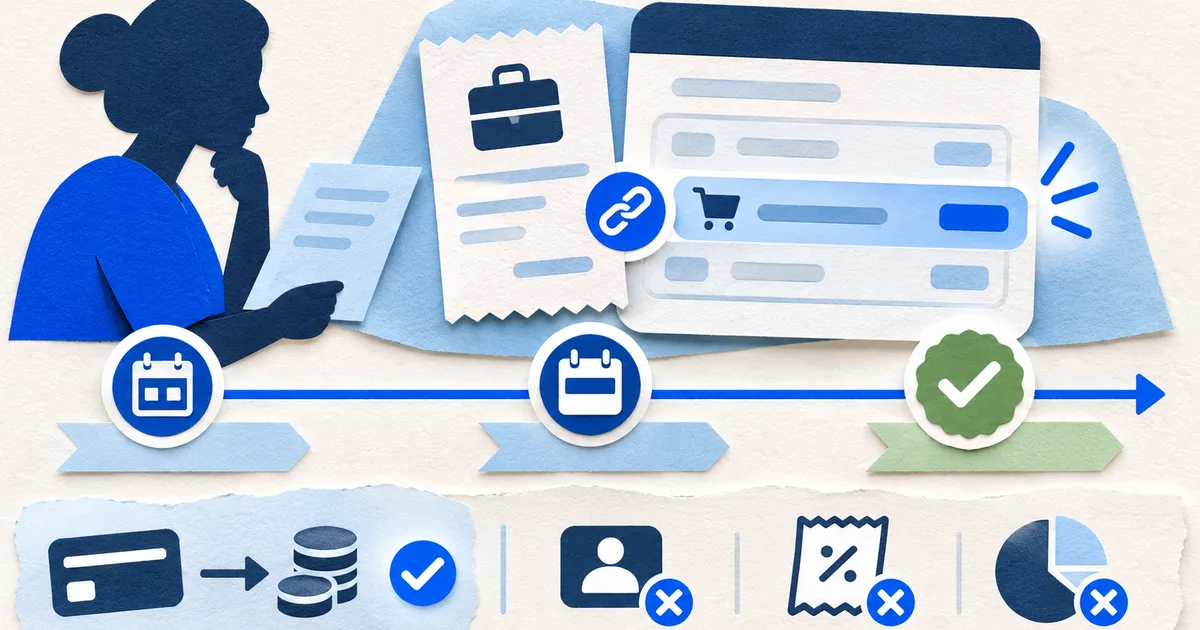
Preserve the statement evidence
Capture issuer description, amount, currency, transaction and posting dates, card suffix, and source page. Keep the original wording even when a merchant is later identified.
Connect refunds and reversals with the original purchase so gross charges are not mistaken for final expense.
Identify the supplier and item
Use receipts, invoices, order records, contracts, and merchant correspondence to establish what was purchased. A marketplace or processor descriptor can hide the actual supplier.
If support is unavailable, record the gap and follow the substantiation rules that apply. Do not invent an item description from the merchant category.
Assemble an expense evidence packet
Make every conclusion traceable from statement row to supporting authority.
Card row
Exact descriptor, amount, currency, dates, suffix, and page.
Purchase proof
Receipt, invoice, order, contract, and supplier identity.
Purpose
User, business connection, approval, and contemporaneous note.
Allocation
Allowable share, method, refunds, and mixed-use treatment.
Review
Ledger match, official guidance, reviewer, and open questions.
Record purpose and ownership
Document who incurred the expense, the activity it supported, and how it relates to the relevant business or reporting purpose. Card ownership alone does not answer those questions.
For employee or shared cards, include approval and reimbursement records. Keep personal and business portions visible when a purchase is mixed.
Apply allocation and accounting treatment
Calculate any allowable share from support and state the method. Separate taxes, tips, refunds, capital items, and foreign conversion when those facts change treatment.
Match the supported amount to the bookkeeping entry and reconcile the card account. The tax conclusion and the card reconciliation are connected but distinct controls.
Review against current authority
Use current official guidance for the jurisdiction, year, taxpayer, and expense type. Rules for meals, travel, home use, vehicles, capital items, and documentation can differ.
Keep the source consulted, review date, preparer, and unresolved questions. This site organizes evidence and does not decide deductibility.
Assume a 240 card charge covers 150 of documented business supplies and 90 of personal goods. Keep the original 240 row unchanged. Attach the itemized invoice, identify the purchaser and purpose, record the supported 150, excluded 90, allocation method, reviewer, and relevant rule. Replacing the source amount with 150 would break statement reconciliation and conceal the personal portion rather than documenting it.
Begin with an expense-candidate queue, not a deduction list. Each candidate should retain descriptor, dates, amount, currency, card suffix, source page, proposed category, missing evidence, refund status, and owner. A merchant that usually sells office products does not establish the items in this purchase, their use, or applicable treatment. The queue directs research while leaving the tax conclusion open.