
Minimum payment
The amount the issuer says must be received by the due date under its payment instructions. It can include past-due amounts or special-plan requirements.
Enter the rule printed in your card agreement or statement. This estimator compares a percentage-based amount with a fixed floor, then adds the interest, fees, and past-due amount you tell it to include.
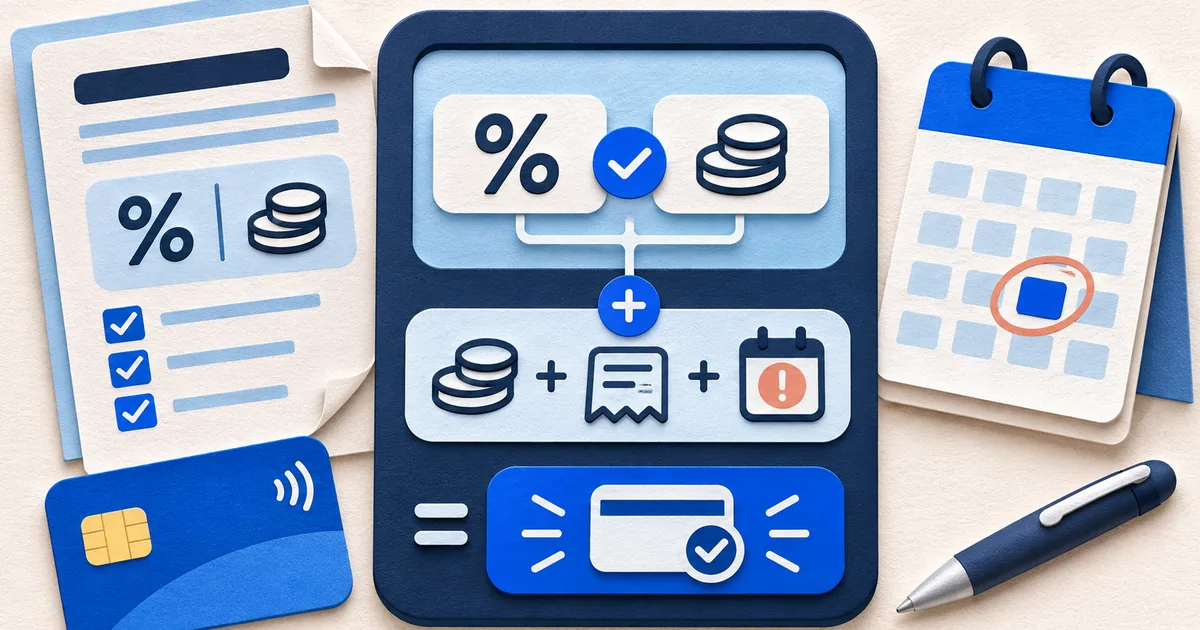
This version calculates the greater of a percentage amount or a fixed floor, then adds entered interest, fees, and past-due amounts. The result is capped at the statement balance.
A statement can show several amounts that answer different questions. The calculator estimates only the required minimum under the rule you enter.
The amount the issuer says must be received by the due date under its payment instructions. It can include past-due amounts or special-plan requirements.
The amount owed when the billing cycle closed. Paying it can have different consequences from paying the minimum, subject to the agreement and account status.
A changing figure that can include later purchases, credits, fees, or payments. It should not replace the issued minimum-payment figure.
For a $2,000 balance, a 1% base equals $20. If the floor is $25 and the disclosed rule adds $18 of interest and fees, the estimate is $43.
The $25 floor wins because it is greater than $20. The estimator then adds $18. If the actual statement shows another amount, read its minimum-payment explanation before changing any input.
A minimum can contain a base calculation, required additions, and account-specific adjustments.
Compare the percentage amount with the fixed floor printed in the terms.
Add interest, fees, or past-due amounts only if the issuer formula says to add them.
A minimum normally cannot exceed the amount owed, so this estimator caps the result at the entered balance.
Promotional plans, installments, over-limit amounts, delinquency, and rounding can change the calculation. The minimum payment and due date guide explains where to verify the controlling statement figures.