
Cash advance statement review
Find the advance, transaction fee, separate APR balance, and interest start date.
This estimate adds the larger of the percentage fee or minimum fee to simple daily interest for the entered period. Exact statement charges can differ because issuer terms, compounding, posting dates, and payments control the result.
Important: Cash advances can have a transaction fee and a separate APR. Interest may begin without the purchase grace period described elsewhere in the agreement.
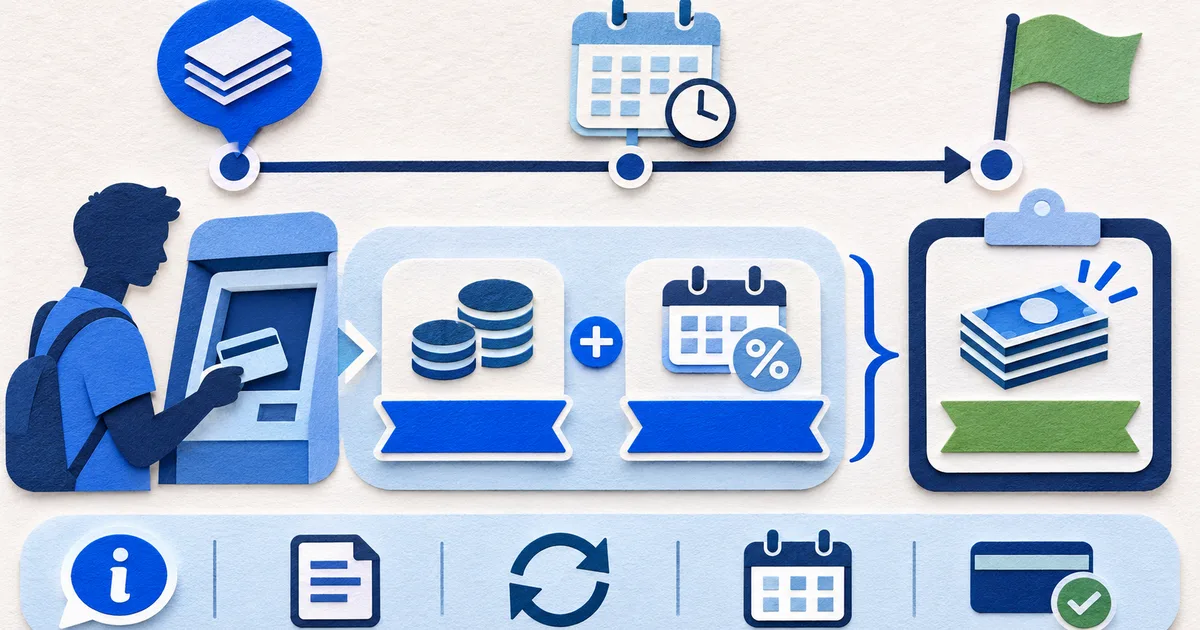
The fee is charged once under the rule entered here. The interest estimate uses simple daily interest on the advance amount for the entered days.
The purchase due date is not a reliable starting point for cash-advance interest. Use the transaction classification, posting date, and payment-allocation record specified by the issuer.
Confirm that the issuer classified the row as a cash advance or cash-equivalent transaction. Preserve the posting date and amount.
Match the percentage and minimum-fee rule to the agreement. A separate ATM operator fee may not be the issuer's transaction fee.
Count days under the issuer's balance method. The calculator uses simple daily interest and does not compound or add the fee to the interest-bearing balance.
Check when a payment actually reduced the cash-advance category. Payment allocation can prevent a whole payment from reaching that balance immediately.
For a $500 advance, a 5% fee with a $10 minimum produces a $25 fee. At 30% APR for 20 days, simple daily interest is about $8.22.
A statement can differ if interest applies to the fee, the posting date changes the day count, interest compounds, or a payment changes the daily balance.
Do not borrow the purchase APR or purchase grace-period wording unless the agreement explicitly applies it to cash advances.
Cash access, convenience checks, gambling-related transactions, or cash-like purchases may receive special treatment under the agreement.
The calculator selects the greater of the entered percentage fee and minimum fee.
Use the posting date and the date the relevant balance was reduced, subject to the issuer's allocation method.
This browser tool does not model compounding, payment allocation, later advances, ATM surcharges, or issuer-specific daily-balance rules. Use the payment allocation reference when the card has more than one APR balance.
| Missing factor | Why it matters |
|---|---|
| Payment allocation | A payment may not reduce this balance on the date or in the order you expect. |
| ATM operator charge | A separate machine fee may not appear as the card issuer's cash-advance fee. |
| Interest on fees | Some balance methods can include charged fees in a balance that accrues interest. |