
Statement balance divided by closing-date credit limit.
Credit Card Statement Health Check for Balance and Cost Signals
Use disclosed statement figures to calculate a small set of descriptive card ratios. The board supplies no grade, universal target, credit-score prediction, or affordability decision.
Preparing your private analysis
Your statement is being secured before analysis begins.
Leave this window open; your private results will load here when ready.
Anchor every number to the same closing date
Use the statement balance, minimum payment, interest, and fees from one issued cycle. Use the credit limit that applied at that closing date. A live current balance or later limit change makes the ratios describe different moments.
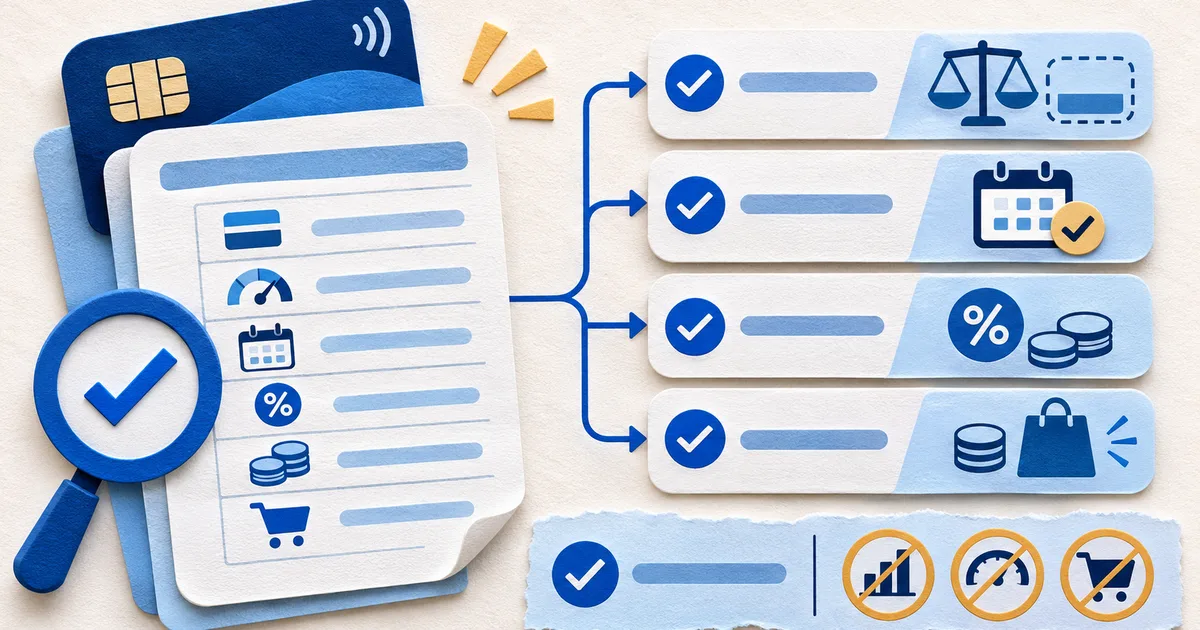
- Evidence windowOne issued billing cycle
- DenominatorsClosing-date limit or statement balance
- InterpretationDescriptive, not predictive
Statement signal board
Enter the statement balance and applicable credit limit.
Interest and fees divided by statement balance.
Minimum payment divided by statement balance.
New charges, interest, and fees less payments and credits.
- Interest and fees entered
- 0.00
- Balance after minimum payment
- 0.00
What each statement signal measures
Every output uses a denominator shown on the page. The ratios describe one issued statement and deliberately avoid universal targets, grades, or approval claims.
| Signal | Calculation | Question it cannot answer |
|---|---|---|
| Statement utilization | Statement balance divided by the credit limit records a closing-date balance ratio. It does not establish when an issuer reported information or how a scoring model treats it. | When an issuer reported the balance or how a score model uses it. |
| Interest and fee share | Interest plus fees divided by statement balance shows how much of the closing amount came from disclosed card costs. A zero balance leaves this ratio unavailable. | Whether the APR, fee, or transaction classification is correct under the agreement. |
| Minimum payment share | Minimum payment divided by statement balance describes the required amount relative to the balance. The issuer agreement, account status, and special plans still control the actual minimum. | Whether paying the minimum is suitable or what future interest will be. |
One-statement signal example
A $1,800 statement balance on a $6,000 limit produces 30% statement utilization. With $27 interest, no fee, and a $60 minimum, the cost share is 1.5% and the minimum-payment share is 3.3%.
Those percentages document the entered cycle. They do not say that 30%, 1.5%, or 3.3% is good, bad, safe, or suitable. A useful review compares the same measures across complete cycles and explains limit changes, promotional balances, disputes, and unusual charges.
Read a change before judging it
A ratio can move because the balance changed, the denominator changed, or the statement classified activity differently.
- Check the limit.A limit increase can lower utilization even when the balance did not fall.
- Check the cycle.A longer cycle or an annual fee can increase costs without describing a permanent pattern.
- Check special balances.Cash advances, transfers, and installment plans can carry separate APRs and payment rules.
Why these signals are not a financial diagnosis
One statement cannot establish income, assets, other debts, available cash, creditworthiness, or future account treatment. The page reports statement arithmetic only.
No score prediction
The worksheet does not model a bureau file, reporting date, scoring formula, lender policy, or approval decision.
Multiple APR balances
Purchase, transfer, installment, and cash-advance balances can have different costs. One combined statement ratio cannot explain each category.
Date sensitivity
The closing balance, current balance, available credit, and reported balance may describe different times. Record the date of every comparison.
Trace each signal to statement rows
Use the analyzer when interest, fees, credits, purchases, payments, or balance movement need to be reconstructed from the issued document.