
Credit Card Statement Utilization Calculator for Reported Balance
Utilization is the selected balance divided by the credit limit, multiplied by 100. This page shows the statement and current ratios separately because they can describe different dates.
- Uses the credit limit you enter
- Keeps statement and current balances separate
- Does not predict a credit score
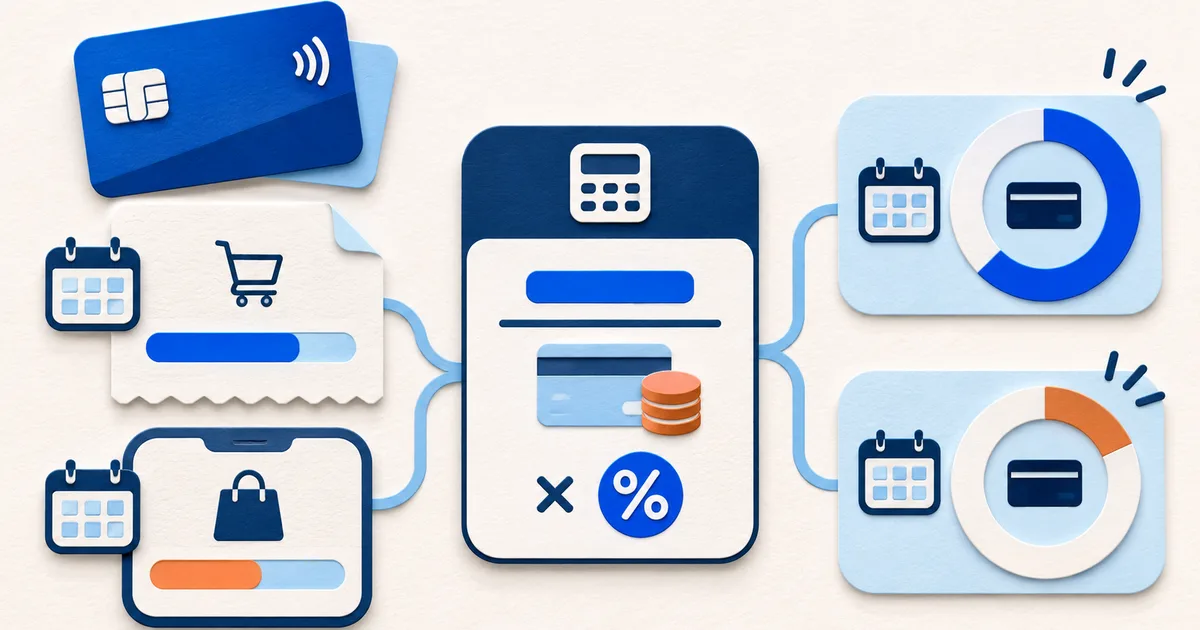
Enter a nonzero credit limit to calculate both ratios.
Keep a dated observation record
A percentage without a date and source is easy to misread. Record the balance label, exact observation time, applicable limit, and whether pending activity was included.
The statement ratio is reproducible from an issued document. A current ratio is temporary and can change after a purchase posts, a payment returns, a credit arrives, or the issuer changes the limit.
If the ratio exceeds 100%: Do not cap the calculation when reviewing the record. Confirm the balance and limit dates, then look for an over-limit balance, a limit reduction, posted fees or interest, a returned payment, or a data-entry error. The meter stops visually at 100%, but the numeric result preserves the actual ratio.
- Statement observation
- Source: issued statement
Date: closing date
Balance state: posted through cycle close - Current observation
- Source: issuer account view
Date: exact time checked
Balance state: document whether pending items are excluded - Limit observation
- Source: statement or issuer account
Date: date limit applied
Change check: note any increase or decrease between observations
One account, two dates, two ratios
A $1,200 statement balance on a $4,000 limit equals 30%. After a $400 payment and $100 of new purchases, an observed current balance of $900 equals 22.5%.
The second ratio does not replace the first. The statement ratio records the closing-date snapshot, while the current ratio records whatever activity the issuer has posted at the time you check.
Interpret the ratio without inventing a target
This page reports arithmetic only. It does not claim a universal utilization target or estimate how any scoring model will treat the balance.
- Numerator
- Choose the statement balance for a closing-date review or the current balance for a current-account snapshot.
- Denominator
- Use the applicable credit limit, not available credit and not the combined limit from unrelated accounts.
- Date label
- Record when both figures were observed so a later comparison uses the same basis.
Boundaries of a single-account ratio
A utilization percentage does not reveal whether a balance was reported, how other accounts are treated, or how a lender evaluates a file. Confirm the numerator with the statement balance and current balance guide. Keep the calculation as an account record, not a promise that changing the balance at one moment will produce a particular credit decision.
- Pending purchases may be outside the current balance.
- A returned payment can change the balance after the calculation.
- An account-level ratio is not a combined ratio across every revolving account.
- A credit limit change makes before-and-after comparisons uneven.